SUMMARY
War-risk premium carried over from the 30-August Larak Island strikes and rose further after the US struck three Iranian oil tankers on 5-September, driving the month's largest single-day moves on 11-September. A lull in Iranian attacks and higher insecurity in the Red Sea saw Saudi Arabia increase Hormuz throughput, pulling prices off their mid-month highs by 18-September. However, that calm broke after Iran's 25-September proposal to reopen the Strait within seven days was rejected by the US the next day. Attacks continued into month-end, with four more vessels struck in the final week of September. Amid such volatility, Brent whipsawed from $102.41 (18-Sep) to $106.13 (24-Sep) to $97.68 (30-Sep) inside of three weeks.
Gasoline Singapore 92 RON led the complex (+23.0% MoM to $136.30/bbl avg), with Naphtha Japan CFR (+14.1% to $903.32/MT) and Propane FE CFR (+17.8% to $878.15/MT) both rallying in step. The propane-naphtha switch spread narrowed to -$25.17/MT from August's -$46.47/MT, moving further from the -$50/MT level that triggers petrochemical feedstock switching, even as freight tightened across the board.
Propane CP prices rose $55/mt to $680/mt and butane by $70/mt to $730/mt in Aramco’s October CP announcement on 29-September. This was the sharpest CP increase since April 2026, when the CP saw a month-on-month rise of $205/mt for propane and $260 for butane due to the onset of the Middle East conflict.
MARKET ACTIVITY
Gasoline
- Window activity for Mogas 92 (100kb) FOB Straits cargoes thinned: 20 bids and 7 offers in September versus 19 bids and 13 offers in August; completed trades fell to 4 from 13.
- Buyers in September were diverse, with all 4 trades going to different trading houses — Mercuria Asia Resources, PTT International Trading, SK Energy International and Gunvor Singapore — one apiece. In contrast, trading in August saw Gunvor Singapore dominate buying, taking 8 of the 13 trades cleared that month; Reliance Global Energy Services and Trafigura each bought 2.
- September's sellers were split, each selling just one lot — Trafigura, Aramco, Union International Trading and Vitol Asia. This compares to August where sellers were concentrated behind PTT (8), Aramco Trading Singapore (3) and TotalEnergies Trading Asia (2).
- Gasoline Singapore FOB 92 RON ran from $119.84/bbl (1-Sep) to a $146.94/bbl high (11-Sep), last trading at $141.42/bbl (30-Sep).
Naphtha
- Window activity flipped from heavily offered to heavily bid: 66 bids and 48 offers in September versus 50 bids and 73 offers in August, with completed trades rising to 8 from 5.
- BP Singapore remained the dominant buyer in both months, taking 4 of September's 8 trades against 3 of August's 5; TotalEnergies Trading Asia bought 2 in each month. Equinor bought once in September, and Vitol Asia — a seller in both months — also bought once in September for the first time.
- ADNOC Global Trading Asia was the dominant seller in both months, selling 5 of September's cargoes against 3 of August's; Vitol Asia sold twice in each month, and Marubeni Petroleum, a new September seller, sold once.
- Naphtha Japan CFR ran from $848.50/MT (1-Sep) to a $982.88/MT high (14-Sep), last trading at $884.63/MT (30-Sep).
LPG
- The Propane FE CFR physical window logged 48 bids against 11 offers for the full month, with 6 cargoes clearing. BWPS was the dominant bidder (15 of 48, 31%), with Satellite International (Singapore) second (10); the offers were led by Gunvor, BWPS and Satellite at two offers each.
- BWPS bought 23kt cargoes delivered 1H October from Gunvor twice, (10-Sep, 15-Sep) and from SKGI once for 2H October delivery (25-Sep), then sold a 23kt cargo delivered 1H November to BP on 24-Sep at October FEI plus $17/MT. Hartree Partners bought a separate 23kt cargo delivered 2H November from Singapore Carbon Hydrogen Energy (SCHE) on 30-Sep at October FEI plus $2.00/MT, and PetroChina Singapore (PCSG) bought the month's only full-size (46kt) cargo for 2H October delivery, from BASF on 1-Sep at September FEI minus $6/MT.
- CME Propane CP swap and futures activity (Middle East hub) surged in September: trade count more than tripled to 60 from 19, while volume nearly tripled to 139MT from 49MT.
PRICE ACTION
Gasoline Singapore 92 RON: Full-month avg $136.30/bbl (+23.0% MoM, +71.2% YoY), +18.0% open-to-close ($119.84 to $141.42/bbl). Monthly high $146.94/bbl (11-Sep), low $119.84/bbl (1-Sep).
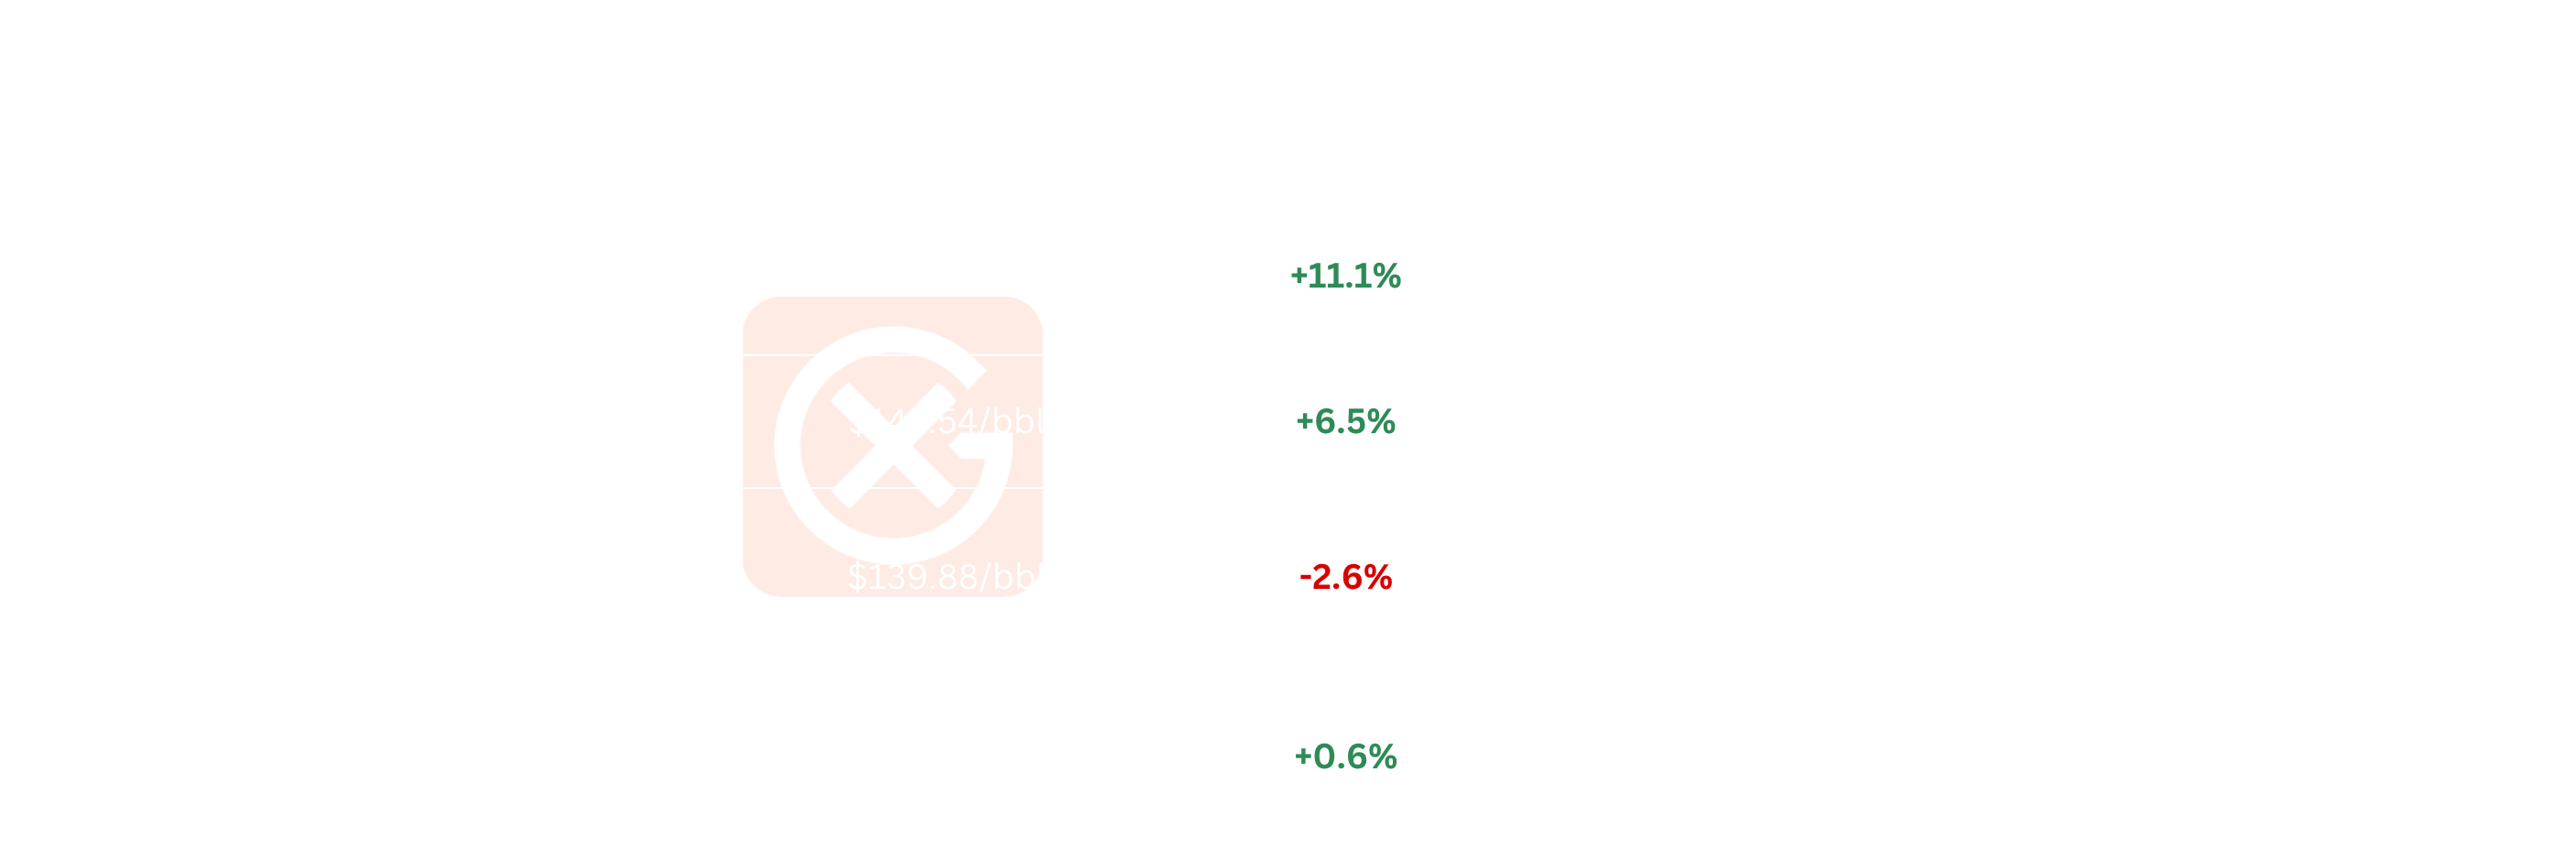
Naphtha Japan CFR: Full-month avg $903.32/MT (+14.1% MoM, +50.4% YoY), +4.3% open-to-close ($848.50 to $884.63/MT). Monthly high $982.88/MT (14-Sep), low $848.50/MT (1-Sep).
- The crack vs Dubai crude cratered to -$21.50/bbl on 16-Sep, its low for the month, before recovering to close at -$6.79/bbl (30-Sep); naphtha's outright price stayed firm through this window while Dubai crude outpaced it.
Propane FE CFR: Full-month avg $878.15/MT (+17.8% MoM, +62.9% YoY), +6.3% open-to-close ($823.75 to $875.25/MT). Monthly high $946.50/MT (15-Sep), low $823.75/MT (1-Sep).
CROSS-MARKET DYNAMICS
- Gasoline 92 RON crack vs Dubai: opened $19.93/bbl (1-Sep), closed $35.23/bbl (30-Sep), a 76.8% intra-month widening against a modest 3.3% MoM average gain from August's $21.95/bbl. Product cracking margins strengthened as Dubai crude eased faster than Singapore gasoline into month-end.
- Naphtha Japan CFR crack vs Dubai: opened -$4.57/bbl (1-Sep), fell to a monthly low of -$21.50/bbl (16-Sep), and recovered to close the month at -$6.79/bbl (30-Sep); the monthly average (-$12.12/bbl) swung deeply negative from August's near-flat +$0.13/bbl.
- Propane FE CFR vs Naphtha Japan CFR switch spread: narrowed to -$25.17/MT (Sep avg) from -$46.47/MT (Aug), closing near parity at -$9.38/MT (30-Sep) as propane outran naphtha into month-end; the spread moved further from the -$50/MT level that triggers petchem feedstock switching.
- Singapore 92-vs-95 RON octane spread: averaged $5.39/bbl in September (95 RON $141.69/bbl minus 92 RON $136.30/bbl) versus $3.54/bbl in August (+52%), though it closed narrower at $4.56/bbl (30-Sep) than the monthly average.
- Middle East CP Propane/Butane (C3/C4) spread: widened to -$38.55/MT average in September from -$22.15/MT in August, before the October CP announcement (29-Sep) deepened it sharply to -$50.00/MT; butane's $70 October CP increase against propane's $55 confirms butane held the firmer demand pull amid tighter supply.
CROSS-REGIONAL DYNAMICS
- Gasoline E/W spread (Eurobob NWE swaps vs SG 92 RON swaps, USD/bbl): Asia's discount to NWE narrowed from -$24.33/bbl at August's close (28-Aug) to -$4.92/bbl at September's open (1-Sep) and finished the month at -$5.51/bbl (30-Sep), so Singapore stayed at a discount to Eurobob. The September average was -$5.63/bbl against -$12.48/bbl in August.
- Propane NWE CIF swaps vs Propane Far East CFR swaps: NWE's discount to delivered Far East narrowed from -$239.25/MT (1-Sep) to -$174.75/MT (30-Sep), as NWE's own month-end rally (+24.9% close-to-close) outpaced Far East's (+6.3%), even though the full-month average discount widened slightly to -$231.33/MT from -$220.76/MT in August.
- Propane FE CFR vs Middle East CP swaps spread: widened from $146.50/MT (1-Sep) to $207.00/MT (30-Sep), touching a $246.00/MT high intra-month, as Asian buyers continued to offset loss of Middle East volumes through long haul purchases form the US Gulf, elevating freight prices, which fed into the delivered Japan price.
- Freight: Naphtha LR2 (ME Gulf-Japan) led gains, +47.2% MoM average to $178.62/MT; LR1 +32.5% to $183.58/MT; Baltic LPG3 (US Gulf-Chiba) +18.0% to $298.67/MT; Baltic LPG1 (ME Gulf-East) +12.3% to $224.83/MT. The broad tightening compounded Panama Canal capacity cuts (Neopanamax to 9 slots/day from 3-Sep, Panamax to 23/day from 15-Sep) layered on top of Hormuz-driven vessel diversions.
CURVE STRUCTURE
Gasoline SG 92 RON Swaps: Steepened through the month. M1 surged +$20.53/bbl while M12 slipped -$0.90/bbl, more than doubling the M1-M12 spread from +$18.78/bbl to +$40.20/bbl.
Naphtha Japan CFR Swaps: a mixed picture as the front M1-M2 spread narrowed while the back end widened.
Propane FE CFR Swaps: Backwardation rose more sharply than naphtha's, widening its M1-M12 spread from +$196.52/MT to +$258.41/MT. The Propane Middle East CP calendar roll steepened even further in relative terms, with its M1-M12 spread nearly doubling from +$121.00/MT to +$191.92/MT as M1 rallied +$64.02/MT while M12 slipped -$6.90/MT.
PRICE VOLATILITY
- The Coefficient of Variation (CV) for naphtha and propane both fell to fresh six-month lows in September (3.93% and 3.72%), despite a month that contained a $134/MT naphtha price range and a 16-Sep crack trough, because the added week of relative calm (W5) diluted the mid-month shock across a longer averaging window.
- Gasoline's CV rose to 6.13% from August's 4.03%, the only one of the three to increase, still carrying the mark of the single 11-Sep session that drove its largest daily move of the period.
SOMETHING TO WATCH
- Attacks in the Hormuz Strait have kept escalating (Cape Dao 23-Sep, Al Funtas 28-Sep, three more vessels including the VLCC Mersin Prosperity 29-Sep, four in the recent week), although Iran was said to be evaluating a new US ceasefire counterproposal after Trump rejected Iran's own 7-day reopening plan on 26-Sep. Watch daily transit counts and whether the counterproposal advances.
- October Aramco CP: propane $680/MT and butane $730/MT (+$55 and +$70, announced 29-Sep), a far larger step-up than propane's modest +$5 move from August to September. Butane is the larger of the two monthly increases amid tighter supplies from the Middle East Gulf. This CP increase resets October term prices from the Middle East higher; even as additional US cargoes flow to Asia. Keep eye out on price reaction as higher prices erode profitability for petrochemical sector while seasonal winter demand is expected to keep prices supported.
Note: All figures, prices and market activity referenced in this report are based on the period covered by this monthly update.