SUMMARY
FAME0 NWE FOB averaged $1,778.43/MT in September (+12.3% MoM, +29.7% YoY), the highest monthly average in the 13-month series, on diesel scarcity rather than biodiesel demand. Collapsed Middle East diesel exports, the Saudi East-West pipeline shutdown and Russia's extended diesel export ban lifted LSGO 17.0% MoM to a 15-Sep high. Gasoil outran biodiesel: the FAME0 diff to LSGO averaged $353.17/MT, roughly half its level a year earlier, and closed at a September low of $245.00/MT. Week 5 turned biodiesel-specific weak as US-Iran truce hopes drained gasoil risk premium: FAME0 fell 3.8% from 25 to 30 Sep while LSGO held flat, and the UCOME-UCO margin halved from its 15-Sep peak to $393.00/MT. The curve bull-steepened, M1 gaining $75.50/MT against M12's $12.75/MT, with M1-M2 spiking to $163.75/MT (24-Sep) before reverting to $55.50/MT. The end-October expiry of Russia's diesel export ban and any Hormuz agreement will decide whether the diff recovers or compresses further.
PRICE ACTION
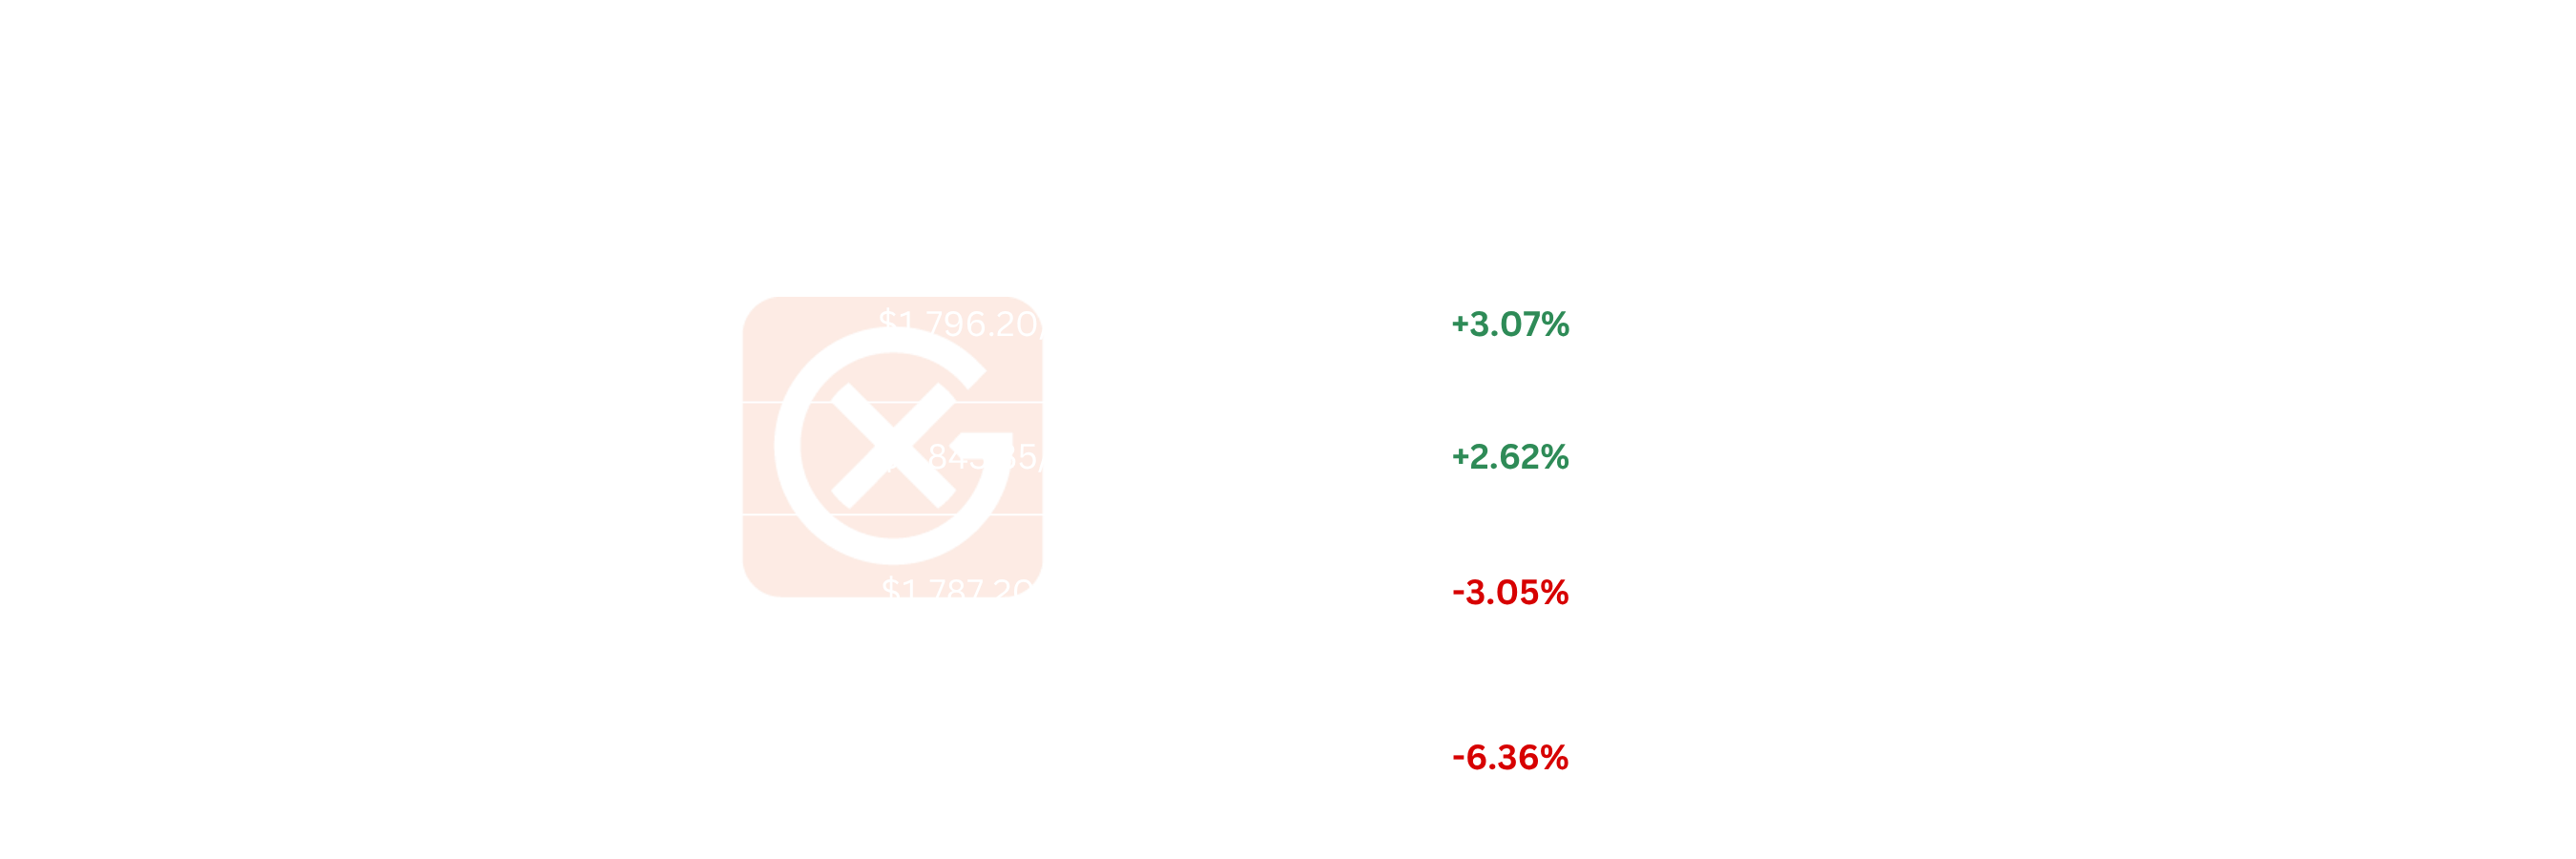
- Opened $1,657.50/MT (01-Sep), closed $1,668.00/MT (30-Sep), $45.75/MT below the August close; avg $1,778.43/MT vs August's $1,583.50/MT (+$194.93/MT), with a $221.00/MT intra-month range
- Largest single-day move: +$133.50/MT (+7.84%) on 03-Sep; the M1 contract fell $5.25/MT the same day
- From the 15-Sep high to the close FAME0 fell $210.50/MT (-11.2%) vs LSGO's $133.75/MT (-8.6%); biodiesel led the unwind
CROSS-MARKET DYNAMICS
- FAME0 diff to LSGO averaged $353.17/MT (Aug $368.71/MT; Sep-25 $676.22/MT), falling from $306.25/MT to $245.00/MT. Mid-month the premium absorbed gasoil swings (+$40.25/MT on 17-Sep as LSGO fell about $50/MT); in Week 5 FAME0 fell from $1,734.00/MT to $1,668.00/MT with LSGO flat near $1,423-1,429/MT, a biodiesel-specific move
- UCOME-UCO margin averaged $485.38/MT (+20% vs Aug $403.01/MT) but fell from $601.75/MT (15-Sep) to a September low of $393.00/MT as UCO kept rising; the UCOME diff to LSGO narrowed from $476/MT to $385/MT
- RME premium to FAME0 averaged +$91.36/MT (Aug +$55.13/MT) and closed at +$195.00/MT, reversing August's -$5.00/MT month-end discount as the winter CFPP premium builds
- HVO Class II rose 4.1% to $2,984.76/MT, the weakest gain among the diesel grades; its LSGO diff narrowed from $1,652.00/MT to $1,559.50/MT while the HVO-UCO margin edged up to $1,543.28/MT
- The SAF 2% jet blend rose 20.7% to $1,574.46/MT, the strongest in the complex, tracking jet; ReFuelEU requires the 2% SAF blend from 2025. Its LSGO diff widened from $124/MT to $187/MT
- UCO averaged $1,419.61/MT (+6.69%) and Tallow $1,039.31/MT (+6.47%); a flat UCO-Tallow spread ($359.44/MT) marks a broad waste-fats move. POME stepped to $1,375/MT on 22-Sep; Ethanol T2 rose 8.1% to €783.17/m³
CROSS-REGIONAL DYNAMICS
- Middle East net diesel exports fell to 390 kb/d in August, about a quarter of pre-war volume (IEA), and the Saudi East-West pipeline shutdown removed the main Hormuz bypass
- The US supplied about half of Europe's seaborne diesel imports in August (Vortexa), so late-month US export-ban talk threatens Europe's main replacement barrel; Russia's diesel export ban, in place since 8 July, now runs to 31 October
CURVE STRUCTURE
- Bull steepening: M1 gained $75.50/MT vs M12's $12.75/MT while M6 fell $18.75/MT; the market priced diesel scarcity as near-term
- M1-M2 widened from $52.75/MT to $163.75/MT (24-Sep) then reverted to $55.50/MT on 30-Sep as M2 rose $92.50/MT in one session; the prompt spike resolved, the M1-M6 steepening held
- If a Hormuz agreement advances, M1-M6 compresses toward its $98/MT month-start; a Russian ban rollover past 31-Oct extends the steepening
PRICE VOLATILITY
- FAME0 CV eased to 3.71% from August's 4.19%, still the second-highest of the six months; HVO (4.44%) and UCO (1.62%) set six-month highs
- Rising feedstock volatility alongside a compressing UCOME margin shows input-cost risk reaching producers; hedging models should assume CV above 3.5% on FAME0 and HVO until diesel flows normalize
SOMETHING TO WATCH
- FAME0 diff to LSGO as the blending-economics canary:
- Observation: the diff closed at $245.00/MT (30-Sep) vs $676.22/MT a year ago
- Why it matters: a Hormuz reopening that pulls LSGO lower should re-widen the diff, as it did mid-month; sustained gasoil tightness alongside softer biodiesel compresses producer economics further
- What to monitor: weekly FAME0-LSGO close; US-Iran talks
- Diesel export policy as the supply canary:
- Observation: Russia's ban runs to 31-Oct and US export restrictions are under discussion
- Why it matters: a restriction on either route tightens prompt LSGO and re-widens M1-M6
- What to monitor: the Russian decision before 31-Oct; any US announcement
- UCOME-UCO margin as the producer-cut canary:
- Observation: the margin fell from $601.75/MT (15-Sep) to $393.00/MT (30-Sep) while UCO rose 6.7%
- Why it matters: the UCOME-UCO margin is the cleanest producer-stress gauge; a sustained close below August's $345.50/MT low signals UCOME run cuts
- What to monitor: weekly UCOME-UCO close
Note: All figures, prices and market activity referenced in this report are based on the period covered by this monthly update.