SUMMARY
European gasoil rose for a third straight month, with ULSD 10ppm NWE CIF averaging $1,499/MT (+16.8% MoM, +109.8% YoY). Half the move was diesel-specific: the crack vs Brent futures widened $14.47/bbl to $98.90/bbl as drone damage cut output at three of Russia’s six largest diesel refineries, forcing Moscow to roll its producer export ban to 31 October, while Hormuz and Red Sea disruption kept Middle East supply constrained. The month’s step came at the open (+$139/MT) as record-low US East Coast stocks put the US in competition with Europe for Gulf Coast barrels. The strength sat in ICE LSGO itself: physical ULSD diffs narrowed and the heating grade closed two-fifths of its gap to ULSD. The back of the curve held its +$450/MT premium and volatility fell to a six-month low. October turns on two binaries: US diesel export restrictions and a further Russian ban rollover.
PRICE ACTION
ULSD NWE CIF rose 16.8% to $1,498.93/MT; the move was made at the open, then consolidated
- Opened $1,459.00/MT (1 Sep), closed $1,488.50/MT (30 Sep), averaged $1,498.93/MT vs August’s $1,283.39/MT (+16.79% MoM; +109.83% YoY vs $714.36/MT)
- Opening step of +$139.00/MT from $1,320.00/MT (28 Aug) as record-low US East Coast diesel stocks and a two-month Saint John refinery shutdown raised competition for the Gulf Coast barrels Europe relies on
- High $1,625.50/MT (15 Sep), low $1,421.50/MT (29 Sep); intra-month range $204.00/MT vs August’s $211.50/MT
- Largest session +$93.50/MT (+6.1%) on 15 Sep, a day after Dated Brent’s +$12.09/bbl jump; retraced -$72.00/MT on 21 Sep
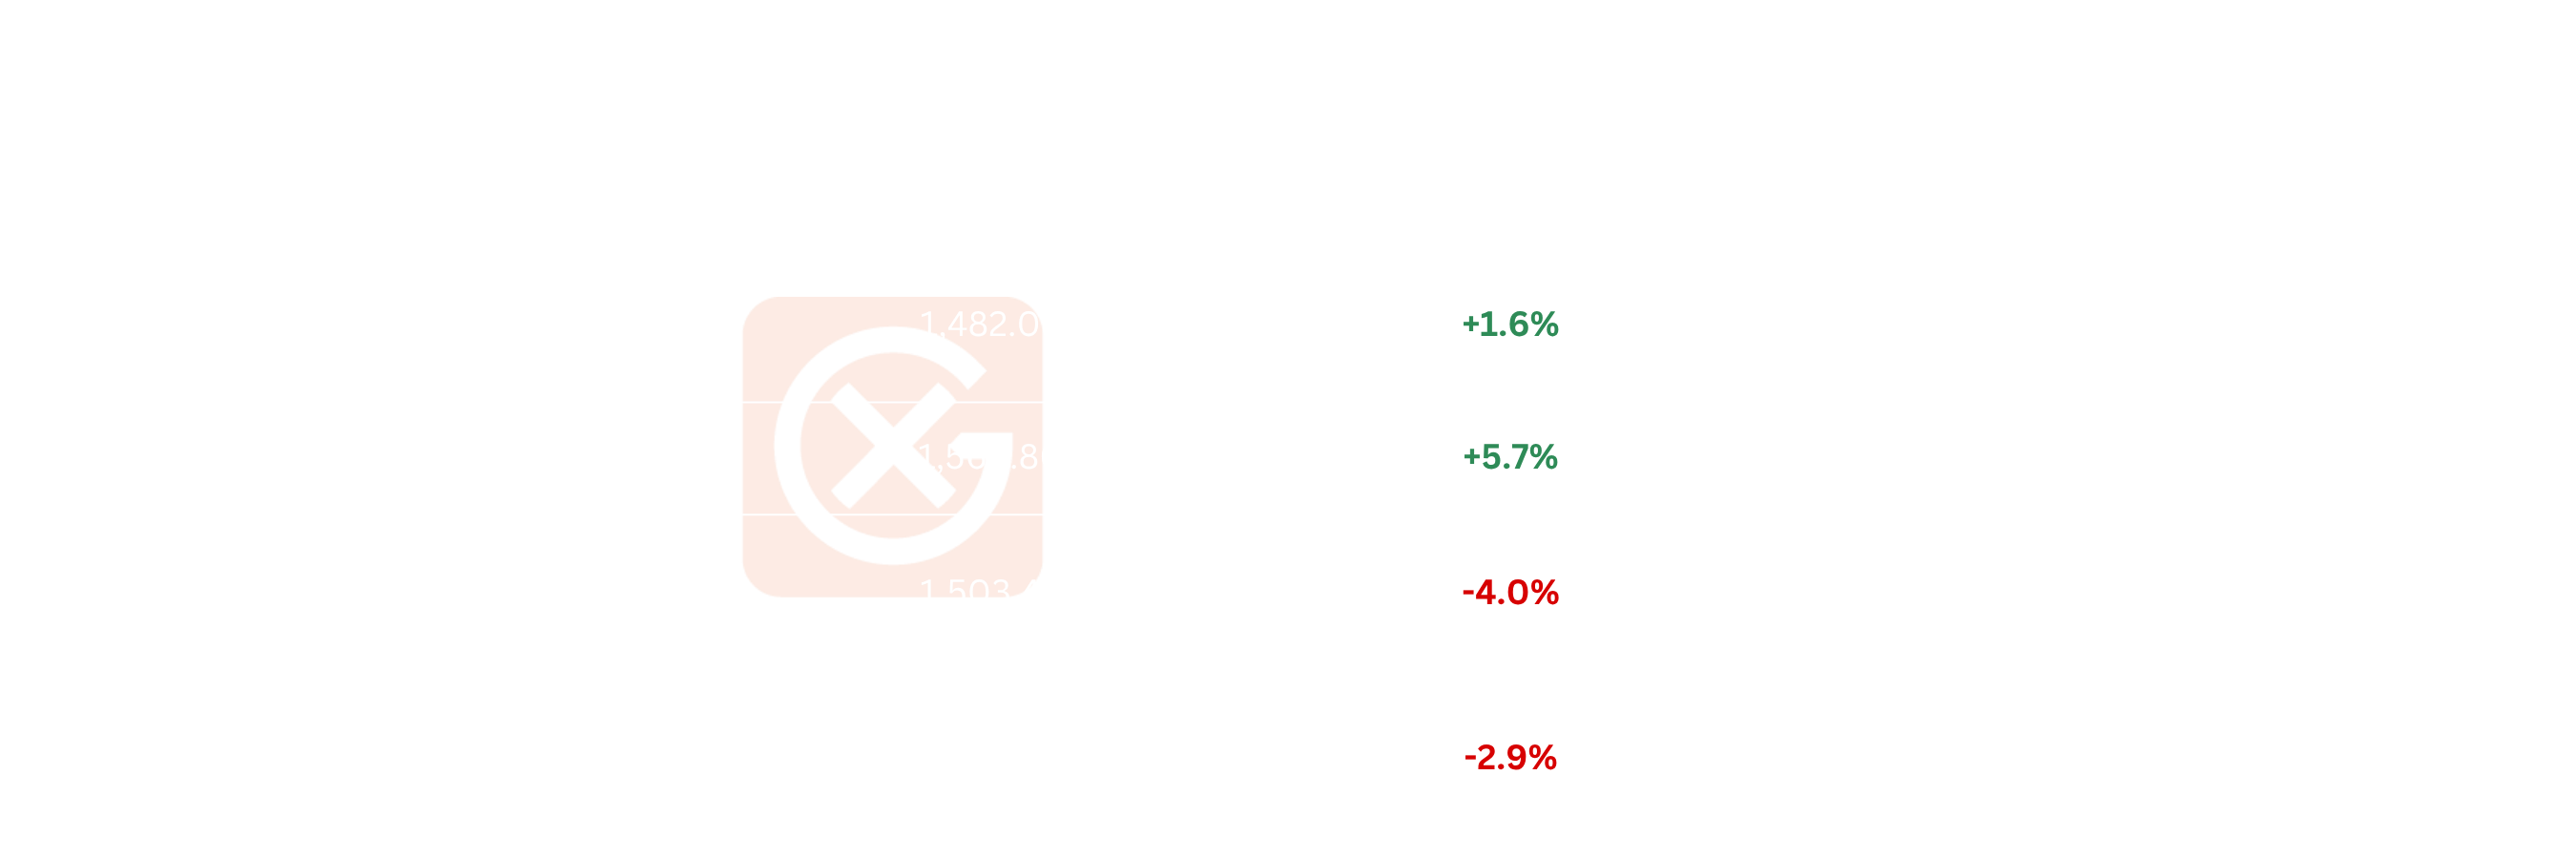
- W39 and W40 eased 4.0% and 2.9% WoW; the market held most of the opening step rather than unwinding it
CROSS-COMMODITY DYNAMICS
- Heating grade caught up with ULSD; the inter-grade CIF spread compressed 39% to $40.78/MT
- ULSD minus Gasoil 0.1% NWE CIF averaged $40.78/MT vs August’s $66.35/MT, touching $14.00/MT (28 Sep) before closing $51.50/MT
- Gasoil 0.1% diffs to LSGO firmed on every basis (NWE CIF -$25.64 to -$8.50/MT; NWE barges -$46.61 to -$27.51/MT; MED CIF +$13.20 to +$18.50/MT), consistent with the Q4 heating bid lifting the wider gasoil pool while ULSD diffs softened
MARKET ACTIVITY
- Cargo trading thinned to three deals as buy-side pressure rose; TOTSA withdrew from the sell side
- Physical: Cargoes (NWE and MED)
- ULSD NWE CIF: trades fell from 9 to 1 as bid/offer rose from 1.30:1 to 4.83:1 (58 bids vs 12 offers); the single trade was Aramco Trading selling to BGN
- ULSD MED CIF: trades fell from 5 to 2 (bid/offer 10.85:1 to 4.56:1), both Aramco Trading buying from Vitol
- Aramco Trading selling NWE while buying MED is intermediary positioning across the two windows, not directional flow
- Gasoil 0.1% cargoes: one trade in each month (September: Vitol to TOTSA, NWE)
- Physical: Barges (ULSD 10ppm, Gasoil 50ppm)
- ULSD: trades rose from 168 to 185 and bid/offer from 1.06:1 to 1.32:1; Shell remained the dominant seller (79 to 100 trades), Vitol the dominant buyer (62 to 83)
- TOTSA, August’s second-largest barge seller (47 trades), dropped out of the top three; BP (19) replaced it
- Gasoil 50ppm: trades fell from 11 to zero
- Derivatives
- Total trades rose from 73 to 93: ULSD CIF NWE vs LSGO 30 to 43; ULSD CIF MED vs LSGO 39 to 29; Gasoil 0.1% CIF MED vs LSGO 5 to 13
- Vitol’s buying nearly doubled (25 to 48 trades); the top seller switched from TOTSA (19 in August) to Mercuria (19)
- TOTSA’s withdrawal from the sell side across barges and derivatives is the month’s regime change
- Trade counts used throughout; volume fields are not comparable across months.
CROSS-MARKET DYNAMICS
- Crack widened $14.47/bbl to $98.90/bbl; diesel strength sat in ICE LSGO rather than physical premia
- ULSD NWE CIF rose $28.93/bbl (7.45 bbl/MT) vs implied Brent futures +$14.46/bbl; the crack widened from $84.43 to $98.90/bbl, making half the flat-price move diesel-specific
- Three of Russia’s six largest diesel refineries cut or halted output in September after drone damage, forcing producer export ban rollovers to 30 September and then 31 October; the non-producer ban runs to January 2027
- Middle East shut-ins rose to 6.7 mb/d in August from 5.0 mb/d (EIA) and Red Sea attacks halved Saudi exports from Yanbu (Vortexa), tightening the East-of-Suez pool behind European distillate imports
- MED CIF crack rose from $89.96 to $101.42/bbl; NWE barges from $82.64 to $96.55/bbl
- ULSD diffs to LSGO narrowed despite the crack (NWE CIF +$40.21 to +$33.66/MT; NWE barges +$26.88 to +$16.14/MT, closing -$5.25/MT): the bid sat in the ICE diesel contract while physical premia lagged
- ULSD cargo-barge spread averaged $17.51/MT vs $13.34/MT; barges traded over cargoes on 7-10 Sep (low -$14.00/MT, 10 Sep), coinciding with the Kaub low-water forecast and the LSGO September expiry, before rebuilding to +$29.75/MT
CROSS-REGIONAL DYNAMICS
- NWE-MED discount halved to -$18.77/MT; the late-August flip did not hold
- ULSD NWE minus MED CIF averaged -$18.77/MT vs -$41.18/MT in August; NWE priced above MED on 2-4 Sep (peak +$26.50/MT) and 24-28 Sep, re-widened to -$56.00/MT (17 Sep) in between, and closed -$29.50/MT
- The MED premium cooled on two reads: MED CIF diff to LSGO +$81.39 to +$52.43/MT; MED assessed-vs-implied +$25.67 to +$6.09/MT
- Russian diesel to the Med fell to 92 kbd in August from 508 kbd in April while US Gulf Coast flows rose to 296 kbd from 86 kbd a year earlier (Vortexa); the MED now draws on the same Gulf Coast barrels the US East Coast is competing for
- Implied Half Daily Structure stayed in contango on all three series (NWE CIF, MED CIF, NWE barges) every day for a third month
CURVE STRUCTURE
Back of the curve held its +$450/MT premium; front narrowing reflects the September contract expiry
- The September contract expired on 10 Sep, so month-start M1-M2 is Sep/Oct and month-end is Oct/Nov; the -$23.75/MT narrowing reflects the expiring contract’s prompt premium rolling off, with M1-M2 still +$50.50/MT
- M1 +$47.75/MT, M6 +$81.75/MT, M12 +$48.75/MT; M1-M12 held between $444.00 and $451.25/MT apart from a one-day dip to $393.25/MT (29 Sep), and widened $34.18/MT to +$443.01/MT on the listing-date-weighted series
- With no Russian volume restart, the deferred premium August flagged as first to compress stayed intact; the 31 October ban expiry is the next test
PRICE VOLATILITY
September CV fell to a six-month low despite a 16.8% rally
- All three grades printed their lowest CV of the window: the repricing came in one step at the open, followed by a narrower range
- Models calibrated to July’s 12% CV overstate day-to-day risk; the tail is a policy binary, with Oxford Economics estimating a US export ban could lift European wholesale prices 40-50%
SOMETHING TO WATCH
- US diesel export restrictions
- Observation: the US President said on 27 Sep a ban is under “very serious” consideration, alongside voluntary export curbs and an excise-tax suspension; US retail diesel hit a record $6.52/gal while ULSD NWE CIF fell 4.0% and 2.9% in the final two weeks
- Why it matters: the US Gulf Coast is the swing supplier to both NWE and MED (296 kbd to the Med in August); curbs remove it while Russian and Middle East supply is already constrained
- What to monitor: White House decision; EIA weekly US distillate exports; ULSD NWE CIF diff to LSGO and the NWE-MED spread
- Russian producer export ban, 31 October expiry
- Observation: rolled monthly twice, with three of the six largest diesel refineries impaired in September; M1-M12 at +$450.25/MT
- Why it matters: a volume restart compresses the deferred premium first; a third rollover keeps the back of the curve priced for structural loss into winter
- What to monitor: the end-October Russian government decree; restart reports from the damaged refineries
- Cargo-barge spread and Rhine levels
- Observation: barges traded over cargoes on 7-10 Sep (low -$14.00/MT) as Kaub was forecast below 25cm; the spread closed +$29.75/MT
- Why it matters: a repeat inversion away from a contract expiry would mark an inland bottleneck widening the barge premium
- What to monitor: Kaub gauge; Insights Global ARA stocks (Thursdays); cargo-barge spread around the 12 Oct LSGO expiry
Note: All figures, prices and market activity referenced in this report are based on the period 1 to 30 September 2026.