SUMMARY
European LPG rallied 29% MoM on both grades in September 2026, with propane averaging $679.53/mt and butane $768.41/mt. Renewed US-Iran strikes and attacks on Saudi Red Sea export infrastructure rebuilt the geopolitical risk premium across the energy complex. The rally was crude-led: propane's crack vs Dated Brent weakened from -$48.33/bbl to -$62.00/bbl, so LPG lagged crude even as it outran naphtha. That outperformance collapsed LPG's feedstock discount, with propane-naphtha closing at -$128.75/mt and butane-naphtha at -$35.25/mt, eroding the cracker economics that pulled LPG into petchem demand over the summer. The winter-grade gasoline switchover restored butane blending value, and coaster premiums widened as inland restocking began. Both forward curves bull-steepened, with propane M1-M12 backwardation nearly doubling to $185.25/mt. With US propane stocks at record levels (EIA), origin supply is not the constraint; a Hormuz reopening deal would unwind the front of both curves first.
PRICE ACTION
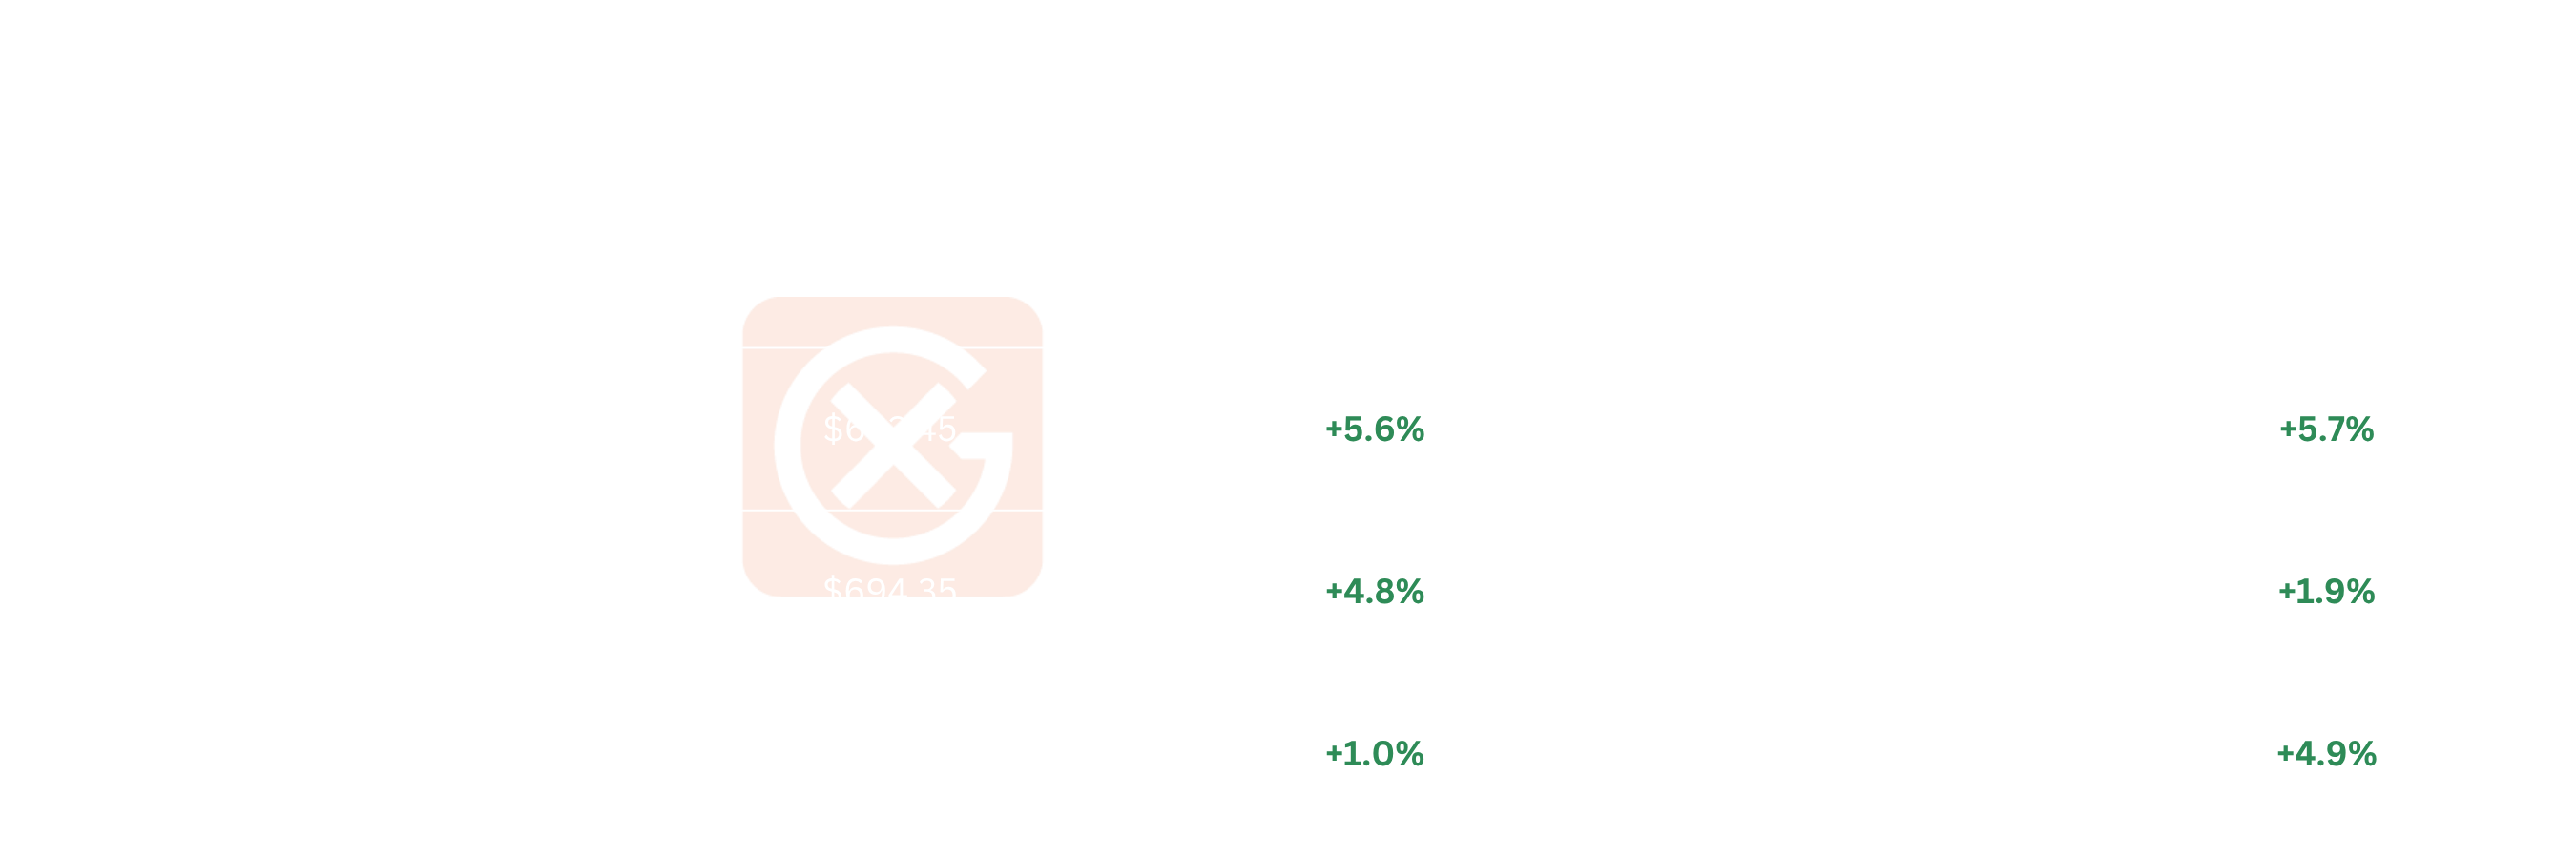
- Propane CIF NWE (GX0000686) rose from $616.25/mt (1 Sep) to $713.25/mt (30 Sep), avg $679.53/mt vs August's $528.42/mt (+28.6% MoM, +44.7% YoY).
- Butane CIF NWE (GX0000687) rose from $702.75/mt to $806.75/mt, avg $768.41/mt vs $595.75/mt (+29.0% MoM, +60.1% YoY).
- The month opened on a gap as strikes resumed: propane +$42.50/mt and butane +$38.50/mt on 1 Sep vs the 28 Aug close.
- Both grades peaked on 24 Sep (propane $728.00/mt, butane $835.00/mt); W2 carried the rally (+5.6% WoW on both), with W4 and W5 propane gains slowing to 1–2% as Hormuz diplomacy tempered the bid.
- Butane swung -$42.50/mt (16 Sep) then +$44.25/mt (18 Sep), consecutive-session reversals consistent with its thinner liquidity.
CROSS-MARKET DYNAMICS
- Propane crack vs Dated Brent (GX0011245) averaged -$62.00/bbl vs -$48.33/bbl in August, bottoming at -$74.99/bbl on 15 Sep as Brent topped $101/bbl; LPG lagged crude, so the premium was crude-led rather than LPG-specific
- Propane-naphtha discount (GX0000736) narrowed from -$217.59/mt (Aug avg) to -$164.39/mt, closing at -$128.75/mt; butane-naphtha (derived) narrowed from -$150.26/mt to -$75.51/mt, closing at -$35.25/mt
- LPG rallied more than twice as hard as naphtha (+29% vs +13.1% MoM); the shrinking discount weakens cracker switching economics and shifts marginal feed demand back toward naphtha
- Physical premium over swaps (GX0000737) averaged +$24.85/mt vs +$0.93/mt in August, peaking at +$42.75/mt on 21 Sep after Saudi Red Sea loadings halted; physical, not just paper, carried the mid-month move
- Propane-butane discount (GX0000738) widened from -$67.33/mt to -$88.88/mt avg, widest at -$115.00/mt on 22 Sep; butane was the tighter molecule as winter-grade specs restored blending demand
- Eurobob's premium over butane (GX0000739) fell from $559.50/mt to $425.50/mt open-to-close, with butane gaining $134/mt on gasoline
- Propane FOB coaster premium over cargoes (GX0011394) closed at +$67.75/mt vs an August avg of +$22.96/mt, consistent with inland winter restocking; butane coasters (GX0011395) flipped from -$132.75/mt to +$165.75/mt on thin prints
CROSS-REGIONAL DYNAMICS
- NWE propane (+28.6% MoM) outpaced FE CFR (GX0000874, +17.8%) and ME CP (GX0000878, +19.4%); NWE-ME moved from a -$44.86/mt August avg to +$8.25/mt at close.
- NWE-FE discount narrowed from -$212.25/mt to -$198.61/mt avg, closing at -$162.00/mt; the Saudi Red Sea outage forced more Gulf exports back through Hormuz, raising Middle East supply risk and pulling Asian buyers toward US barrels, which Europe had to price up to retain.
- A narrower discount to Asia reduces the incentive to divert US cargoes east, supporting NWE supply into Q4.
CURVE STRUCTURE
- Bull steepening on both curves: propane M1 +$116.00/mt vs M12 +$28.25/mt (4.1x); butane M1 +$125.25/mt vs M12 +$34.00/mt (3.7x).
- Butane reversed August's compression (M1-M2 +$1.00/mt at end-August); tightness has moved back into the prompt, in line with propane.
- With M12 nearly flat, the premium sits on the front; a de-escalation compresses M1-M2 first.
PRICE VOLATILITY
SOMETHING TO WATCH
- Hormuz reopening talks as the binary catalyst:
- Observation: Tehran has received a US proposal on reopening Hormuz; propane M1-M2 at +$28.00/mt
- Why it matters: a deal strips the front-loaded premium; M1-M2 back below +$9.00/mt (1 Sep level) would confirm the September premium has fully unwound
- What to monitor: weekly M1-M2 close; resumption of Saudi Red Sea loadings
- LPG-naphtha discount and cracker switching:
- Observation: butane-naphtha at -$35.25/mt, propane-naphtha at -$128.75/mt
- Why it matters: if butane reaches parity with naphtha, crackers switch away and butane loses its petchem floor, leaving blending as its main support
- What to monitor: weekly closes vs August avgs (-$150.26/mt butane, -$217.59/mt propane)
- US origin length vs the Asia pull:
- Observation: US propane stocks at a record 110.5 MMbbl in early September, 25% above the five-year average (EIA)
- Why it matters: ample origin supply caps the NWE physical premium while the arb favors Europe; NWE-FE widening back past the -$212/mt August avg would divert cargoes east and lift it
- What to monitor: EIA weekly propane stocks and exports; GX0000737 weekly close
Note: All figures, prices and market activity referenced in this report are based on the period covered by this monthly update.