SUMMARY
SAF Neat HEFA NWE FOB Barges rose 7.83% MoM in September to average $2,911.35/MT (+7.70% YoY), but the gain was front-loaded: the price peaked at $3,112.25/MT on 15-Sep, the week Saudi Arabia shut its East-West pipeline (the kingdom's main Hormuz bypass), and closed at $2,805.50/MT after Riyadh rerouted crude through Hormuz. The clearest signal was again the green premium: Jet FOB rallied 21.2% MoM, 2.7x SAF's gain, as Gulf disruption and a tight diesel complex lifted fossil distillates, and the premium closed at a monthly low of $1,219.50/MT. Within the HEFA complex, the SAF-vs-HVO discount narrowed on average to -$73.41/MT but swung $404.50/MT intra-month and closed at -$165.25/MT, back at its August level. The order book rebalanced toward bids and trades returned on 17-Sep, anchoring the month's largest single-day fall, while the HEFA producer bid seen in July and August was absent. The curve bear-steepened, with M1-M12 narrowing to $250.50/MT as the front fell harder than the back. The forward watch is whether expected Q4 easing in jet tightness rebuilds the green premium, and whether the month-end HVO premium keeps producer capacity tilted away from SAF.
MARKET ACTIVITY
- Order book rebalanced toward bids and trades returned, but offers set the close
- The book shifted from August's offer-dominated skew toward a more balanced stance, while remaining offer-weighted
- Completed trades returned on 17-Sep after none printed in August; trade prices ($2,901.67/MT outright equivalent) aligned with the GX assessment of $2,901.75/MT that day, so the month's largest single-day fall (-$174.00/MT) was set by confirmed trades rather than indications
- Intermediary positioning: integrated majors moved from almost entirely offer-side in August to quoting both sides, alongside trading houses and a refiner also active on both sides; two-sided participation reflects positioning rather than directional flow
- Regime change: the HEFA producer that bid in both July and August did not appear in September
- Seller offers stepped down through the month; the final offer on 30-Sep ($2,805.55/MT) set the $2,805.50/MT close, with the last bid well below
Note: no SAF bids, offers or trades printed 18-25 Sep.
PRICE ACTION
SAF FOB peaked mid-month and gave back the rally; W4 broke the pattern at -5.37% WoW
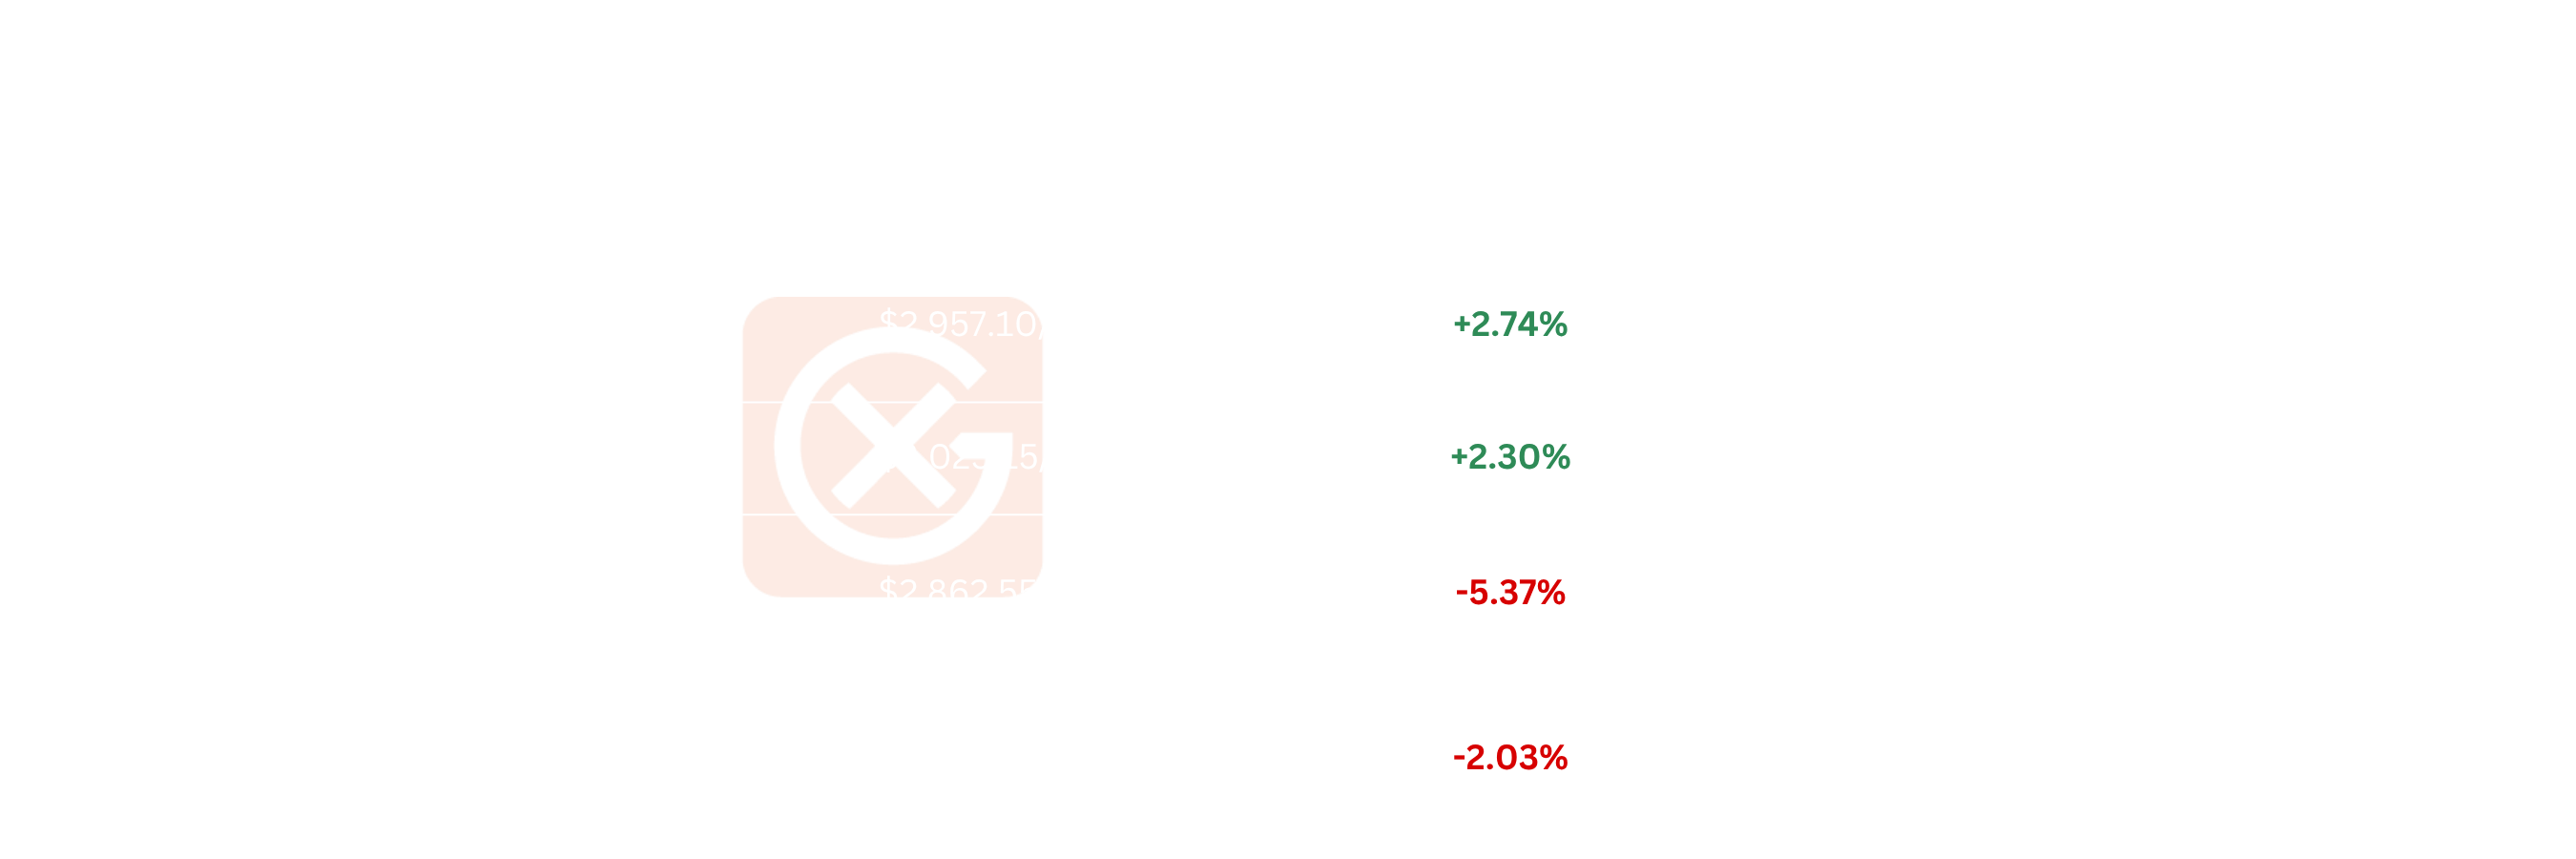
- Opened $2,884.25/MT (1-Sep), closed $2,805.50/MT (30-Sep), averaging $2,911.35/MT vs August's $2,699.93/MT (+$211.43, +7.83% MoM); up 7.70% YoY vs September 2025's $2,703.26/MT
- Intra-month range of $336.50/MT, wider than August's $281.00/MT
- The 15-Sep peak coincided with peaks in Jet FOB ($1,721.75/MT) and HVO ($3,212.00/MT), following the 11-Sep closure of the East-West pipeline, which carries up to 5mb/d to the Red Sea; the shared timing points to a complex-wide risk bid rather than a SAF-specific driver
- The -$174.00/MT (-5.66%) fall on 17-Sep followed Saudi Arabia rerouting crude through Hormuz via ship-to-ship transfers, easing fears of a prolonged outage
CROSS-MARKET DYNAMICS
- Jet outran SAF 2.7x; green premium closed at its monthly low
- Jet Fuel NWE FOB Barges averaged $1,547.17/MT, up from $1,276.19/MT in August (+21.2% MoM), against SAF's +7.83%
- Mechanism: Gulf and Bab el-Mandeb disruption kept Middle East flows below normal while refinery margins widened and record diesel prices pulled jet higher; SAF's mandate- and cost-driven pricing responded less, mechanically narrowing the premium
- Green premium averaged $1,364.18/MT vs $1,423.74/MT (-4.2% MoM); high $1,503.75/MT (11-Sep), close $1,219.50/MT (30-Sep), the monthly low and below August's $1,362.75/MT low
- SAF-vs-HVO allocation spread averaged -$73.41/MT vs -$166.84/MT, briefly flipping to a +$132.50/MT SAF premium on 7-Sep before deepening to -$272.00/MT on 17-Sep; it closed at -$165.25/MT, leaving HVO's premium intact at month-end
- HVO Class II averaged $2,984.76/MT (+4.1% MoM), consistent with diesel-pool tightness supporting renewable diesel over SAF
CURVE STRUCTURE
Bear steepening; M1-M12 narrowed $107.75/MT as the front sold off harder
- M1 (Oct-26) fell $319.25/MT vs M12 (Sep-27) -$211.50/MT; the front led the decline, narrowing backwardation from the front end
- M1-M12 at $250.50/MT sits below the module's typical $400-500/MT range for a second consecutive month-end (August: $280.00/MT)
- Liquidity thins past M6; read the M12 leg as indicative rather than firm structural repricing
Note: M1-M12 month-start uses 2-Sep; the 1-Sep M12 print ($2,293.50/MT) corrected $306.25/MT the next session and is excluded. M1-M2 and M1-M6 use 1-Sep.
PRICE VOLATILITY
September CV of 3.17% held within the six-month range despite the mid-month spike
- CV rose 0.12pp from August and sits within the 1.44-9.70% six-month range; the +7.83% MoM average rise and the -5.66% session came without a volatility regime shift, so hedging calibrated to the summer range remains valid
SOMETHING TO WATCH
- Green premium as the compliance-value canary:
- Observation: premium closed at $1,219.50/MT (30-Sep), at the low end of the module's normal $1,000-1,500/MT range
- Why it matters: Kpler expects less jet tightness in Q4 as European aviation demand falls from November and Asian cargoes arrive; easing jet would rebuild the premium, while renewed Gulf disruption would push it toward the bottom of the range
- What to monitor: daily SAF FOB vs Jet FOB; East-West pipeline restart status; Asian jet arrivals into Europe (Kpler)
- SAF-vs-HVO spread as the capacity-allocation canary:
- Observation: spread closed at -$165.25/MT after a $404.50/MT intra-month swing
- Why it matters: a persistent HVO premium into Q4 keeps HEFA producer incentive tilted toward HVO, tightening SAF supply into year-end compliance
- What to monitor: daily SAF-vs-HVO spread; producer capacity-allocation disclosures
- Feedstock exposure as the cost-floor canary:
- Observation: UCO closed at $1,415.00/MT (30-Sep); the UCO-to-SAF margin closed at $1,390.50/MT, flat vs August's $1,394.25/MT close
- Why it matters: with 85% of EU SAF feedstock imported in 2025 and 61% from China (EASA), import-market UCO moves transmit directly into SAF cost
- What to monitor: weekly UCO NWE FOB vs SAF FOB; biodiesel producers approaching the Annex IX B blend cap
EXTRAS
- UCO NWE FOB averaged $1,406.02/MT vs $1,335.60/MT in August (+5.3% MoM), closing at $1,415.00/MT; a UCOME-UCO spread above $400/t let biodiesel producers bid UCO higher as ICE gasoil volatility widened biodiesel margins
- UCO-to-SAF margin widened on average to $1,505.33/MT (+$141.00) as SAF's rally outpaced feedstock, but the gain was gone by the close, leaving producer economics where August ended
Note: All figures, prices and market activity referenced in this report are based on the period 1 to 30 September 2026.