On paper, Algeria looks like the gas supplier Europe needs. It has large reserves, pipelines that run straight into Spain and Italy, and decades of experience selling to European buyers. Yet markets tend to perceive it as a source of risk, largely because geopolitics is embedded in the mix. This paradox is not noise in the market, it is a signal which we can try to measure. The sections below explain why, and what it means for anyone who trades, hedges or models European gas.
Two Algerias, one supplier
Europe effectively deals with two different versions of Algeria:
On paper, Algeria is a stabilizer.
- It is the EU's second-largest supplier of pipeline gas.
- Its pipelines into Italy and Spain can carry 43.7 billion cubic meters (bcm) a year.
- Those pipelines have spare capacity.
- It has long-standing supply contracts with European buyers, and its coast is a short distance from Barcelona.
In practice, Algeria can act less as a stabilizer and more as an amplifier of uncertainty.
- Its exports can respond as much to politics as to price.
- One of its export pipelines has been shut for diplomatic reasons, and another runs at only 60% of capacity.
- As of 2025, Algeria uses more gas at home than it exports.
- The resulting risk falls mainly on Southern Europe. It tends to show up in how much gas arrives and by which route, more than in prices.
The gap between these two pictures does not appear to be temporary, it looks increasingly structural.
The fundamentals are strong
The case for Algeria as a stabilizer is real. In 2025 it supplied 18.5% of the EU's pipeline gas imports. Only Norway supplied more, at 54.4%, and Russia came third at 9.8%. Once LNG is included, North Africa accounted for 12.7% of all EU gas imports, behind Norway (30.9%), the US (26.2%) and Russia (12.5%). The TransMed pipeline, which runs to Italy via Tunisia, can carry 33.5 bcm a year on its own. Standard market models assume a simple chain reaction. When European demand rises, prices rise, and Algeria exports more to capture those higher prices. Algeria does not always follow that pattern.
Capacity is there. The gas is not flowing.
This problem is not new. In 2014 there was no war in Ukraine, no supply crisis, and no pipeline closures. Even so, TransMed carried only 10.2 bcm, or 30% of its capacity, and Algeria's export pipelines as a whole ran at 52%. Underused capacity appears to be a long-standing feature of the system rather than something that started in 2022.
By 2025 TransMed had recovered to 60% of capacity (20.1 bcm). That was still well short of full, at a time when Europe was looking for every non-Russian molecule it could find. Medgaz, the direct pipeline to Spain, ran at a record 91%. In the same year, from the same supplier, the route to Spain was full while the route to Italy was 40% empty.
The Maghreb-Europe pipeline (MEG), which ran to Spain through Morocco, was operating at 91% when Algeria shut it in October 2021. It was Algeria's busiest pipeline, so closing it removed capacity that was being used, not spare capacity.
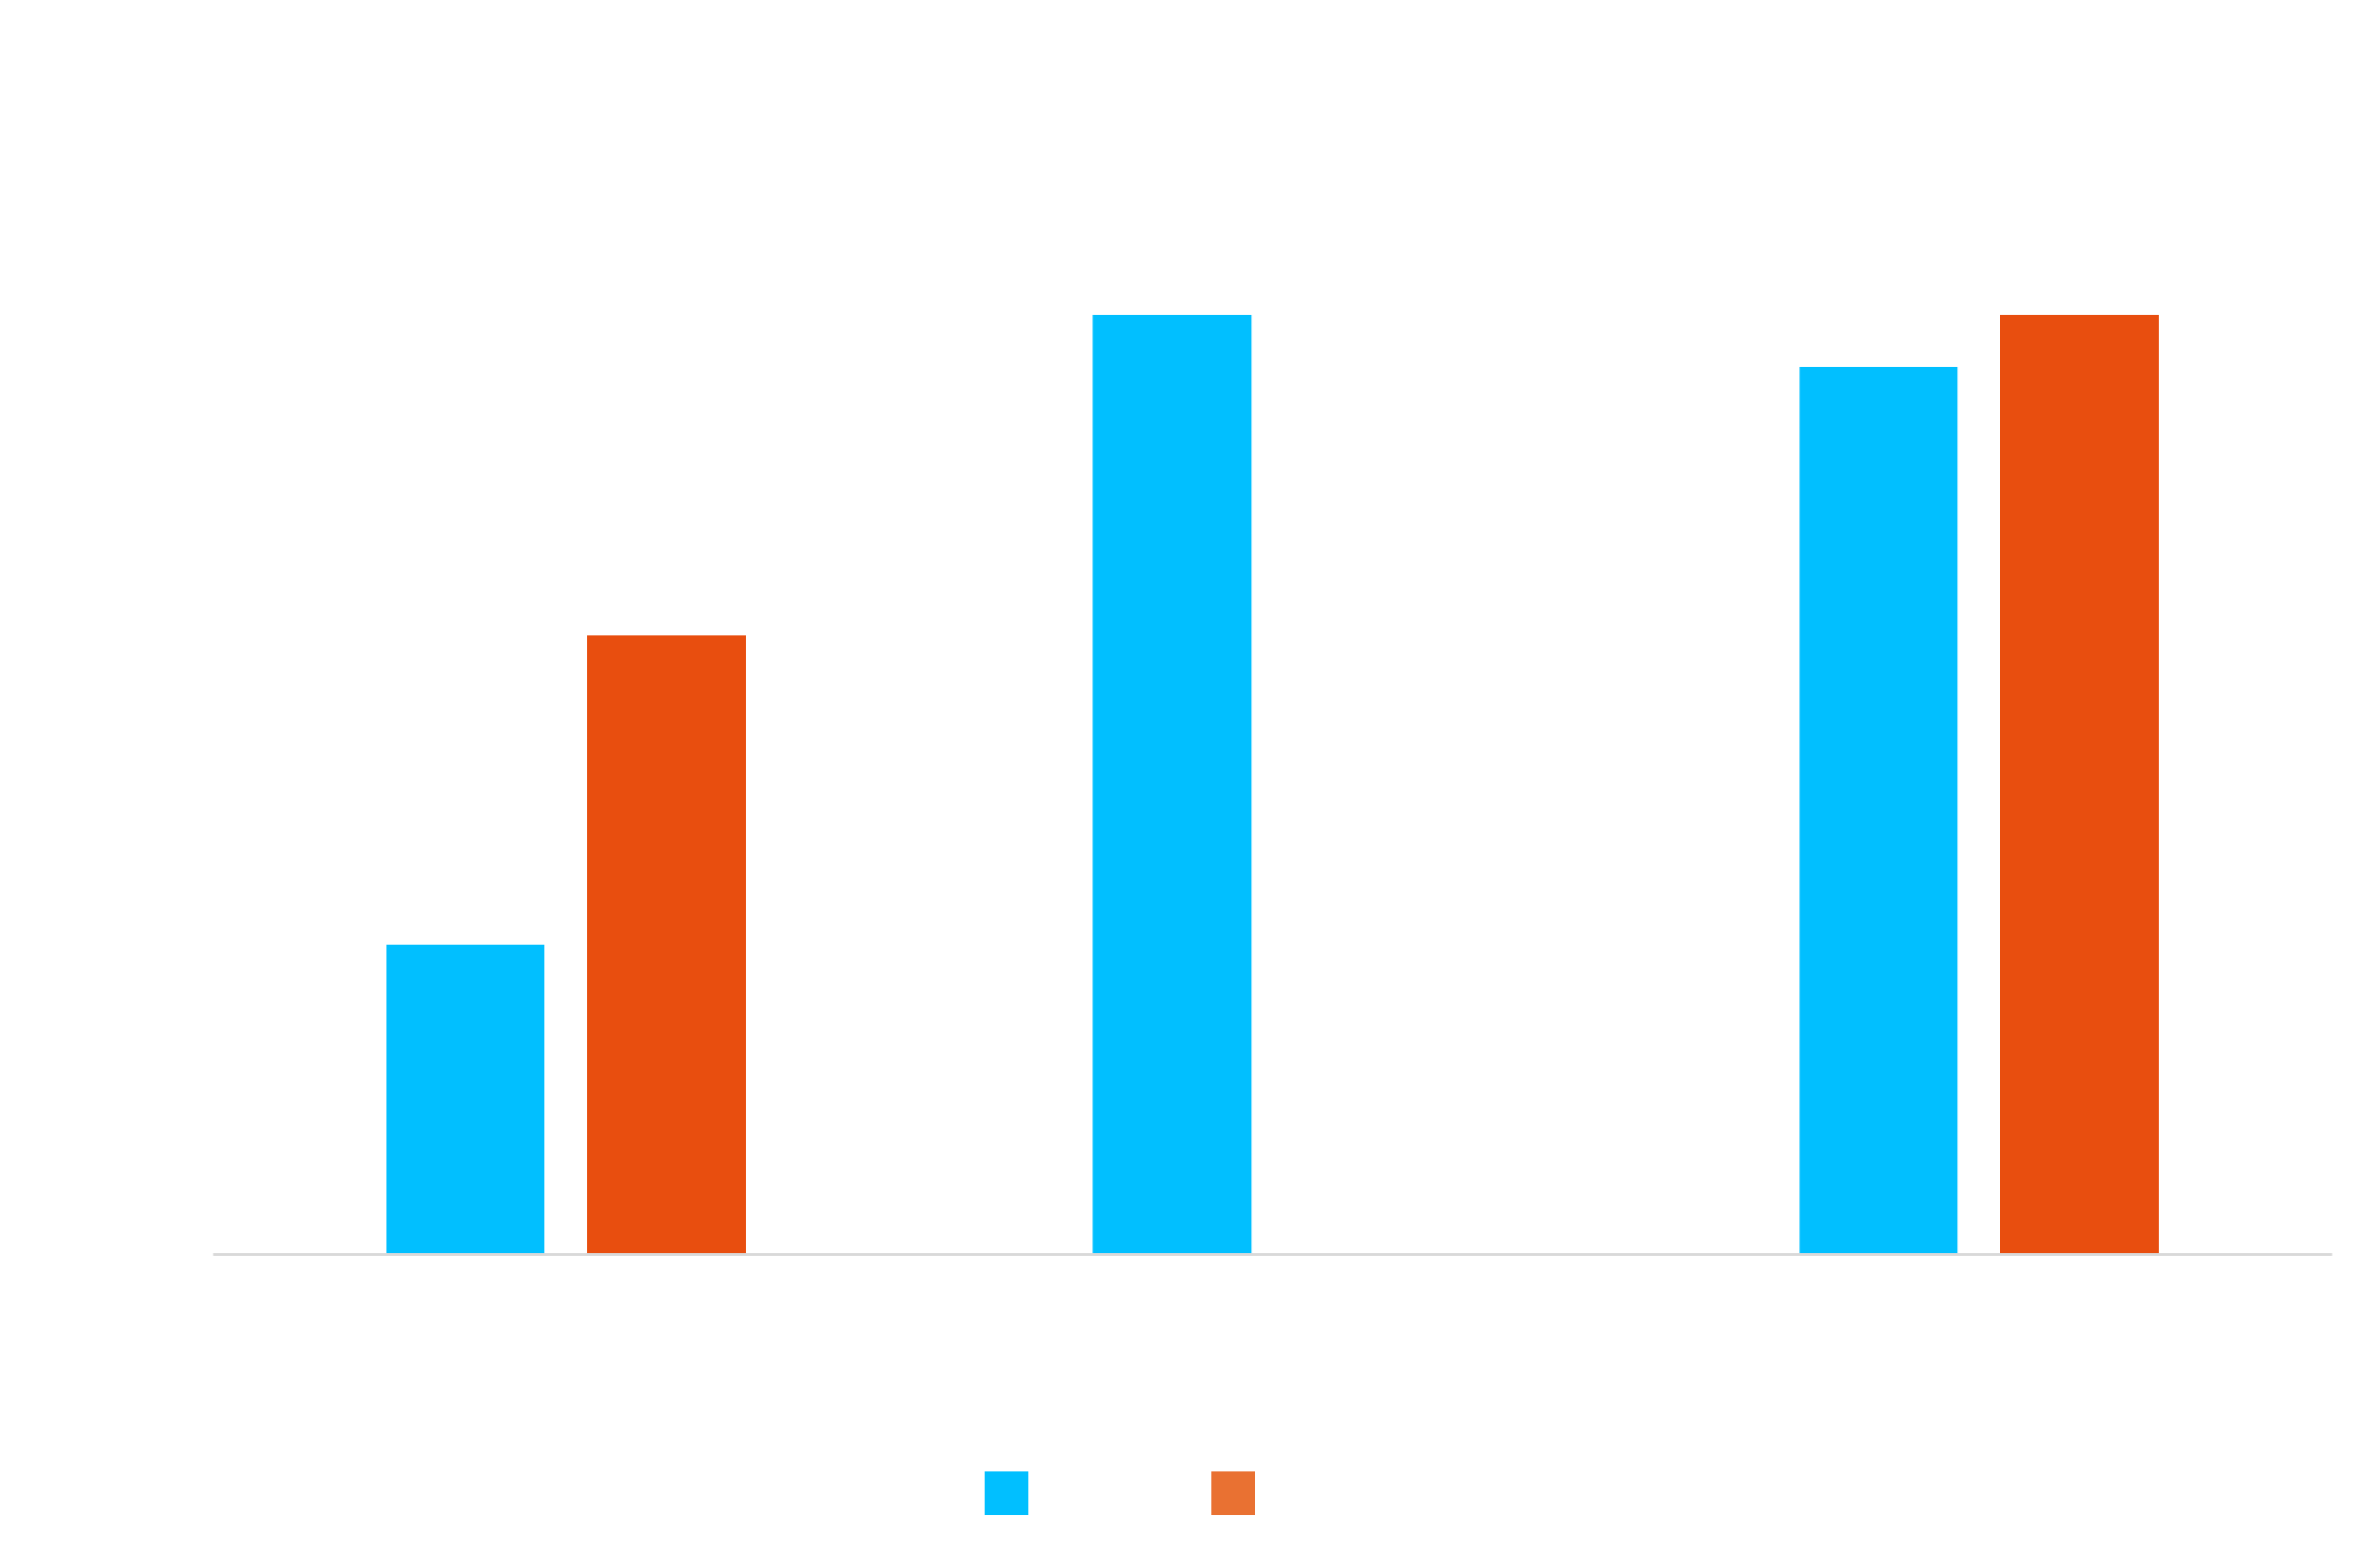
Domestic demand is becoming an increasingly important constraint. In 2025 Algeria used 57.3 bcm at home and exported 46.1 bcm, the first time it consumed more gas than it sold abroad. In the same year, production fell 2.5% and LNG exports fell 18%, to their lowest level in 20 years.
Four geopolitical layers stack onto every molecule
There are four separate sources of political risk behind Algerian gas:
- Regional rivalry. Algeria and Morocco have no diplomatic relations. Their dispute over Western Sahara now shapes decisions about infrastructure, including pipelines.
- Great-power alignment. Russia supplied 81% of Algeria's arms imports in 2017-2021. By 2021-2025 that share had fallen to 39%, with China at 27%, according to SIPRI. Algeria's ties with Moscow appear to be loosening, with Algeria diversifying toward Beijing rather than the West.
- Supply weaponization. Past decisions suggest Algeria is willing to cut or redirect gas flows when the political stakes are high.
- Sahel instability. Niger and Mali sit directly on the route of Algeria's most important future project, the Trans-Saharan pipeline.
Markets can usually price any one of these risks on its own. What is harder to price is the combination. The four layers interact, and that makes Algeria's supply behavior difficult to predict.
Gas and diplomacy: the MEG pipeline closure
The MEG closure is the most visible example. In October 2021, during a diplomatic rupture with Morocco over Western Sahara, Algeria let the pipeline's contract expire. Gas for Spain and Portugal was moved onto Medgaz and TransMed, and Iberia lost one of its supply routes, with no sign yet of it returning.
Since mid-2022 the pipeline has run in reverse, carrying regasified LNG from Spain to Morocco. A pipeline built to export Algerian gas has, in effect, become a diplomatic tool.
Booking data shows the scale of the change. Contracted capacity at Tarifa, where the MEG reaches Spain, fell from 75,548 GWh in 2021 to zero in 2022. At Almería, where Medgaz arrives, contracted capacity rose by only 15,979 GWh. Medgaz made up only a fraction of what was lost. A purely commercial decision would be unlikely to leave a working pipeline idle for five years.
Is this gas weaponization?
Not everyone agrees that it is. Tahchi (2024) argues that Algeria has never used gas to coerce anyone. When Algiers banned imports from Spain in 2022, it explicitly excluded gas, and it honored every contract. Escribano (2025) adds that tensions with Morocco have not been identified as a threat to the gas sector, and that weak TransMed flows in 2024 were partly caused by low demand in Italy.
It is important to be clear about what this does and does not mean. Algeria has a long track record as a reliable supplier and has consistently honored its contractual commitments to European buyers, including through periods of regional tension. The uncertainty lies less with the supplier than with the routes. Southern European buyers value the ability to switch between supply routes, and route availability is where geopolitical factors can come into play.
Why supply behavior is hard to predict
None of this means Algeria is acting irrationally. It is balancing four powers whose interests pull in different directions:
- Russia provides arms and strategic depth.
- The European Union is its largest gas market, and Algeria would struggle to replace that revenue.
- The United States applies sanctions pressure over Algeria's purchases of Russian arms.
- China offers capital, infrastructure and a third option.
Export decisions have to balance all four relationships, and that involves factors standard gas market models do not easily capture. The political risk does not simply disappear, so the real question is where it shows up.
Two readings of the same spread
A hub spread is the price difference between a regional gas hub, such as Spain's PVB or Italy's PSV, and the Dutch TTF benchmark. If Algerian politics adds risk, you would expect it to widen these spreads. The analysis covered every Algeria-specific event for which spread data exists.
The clearest moves in the data were linked to physical disruptions rather than political events:
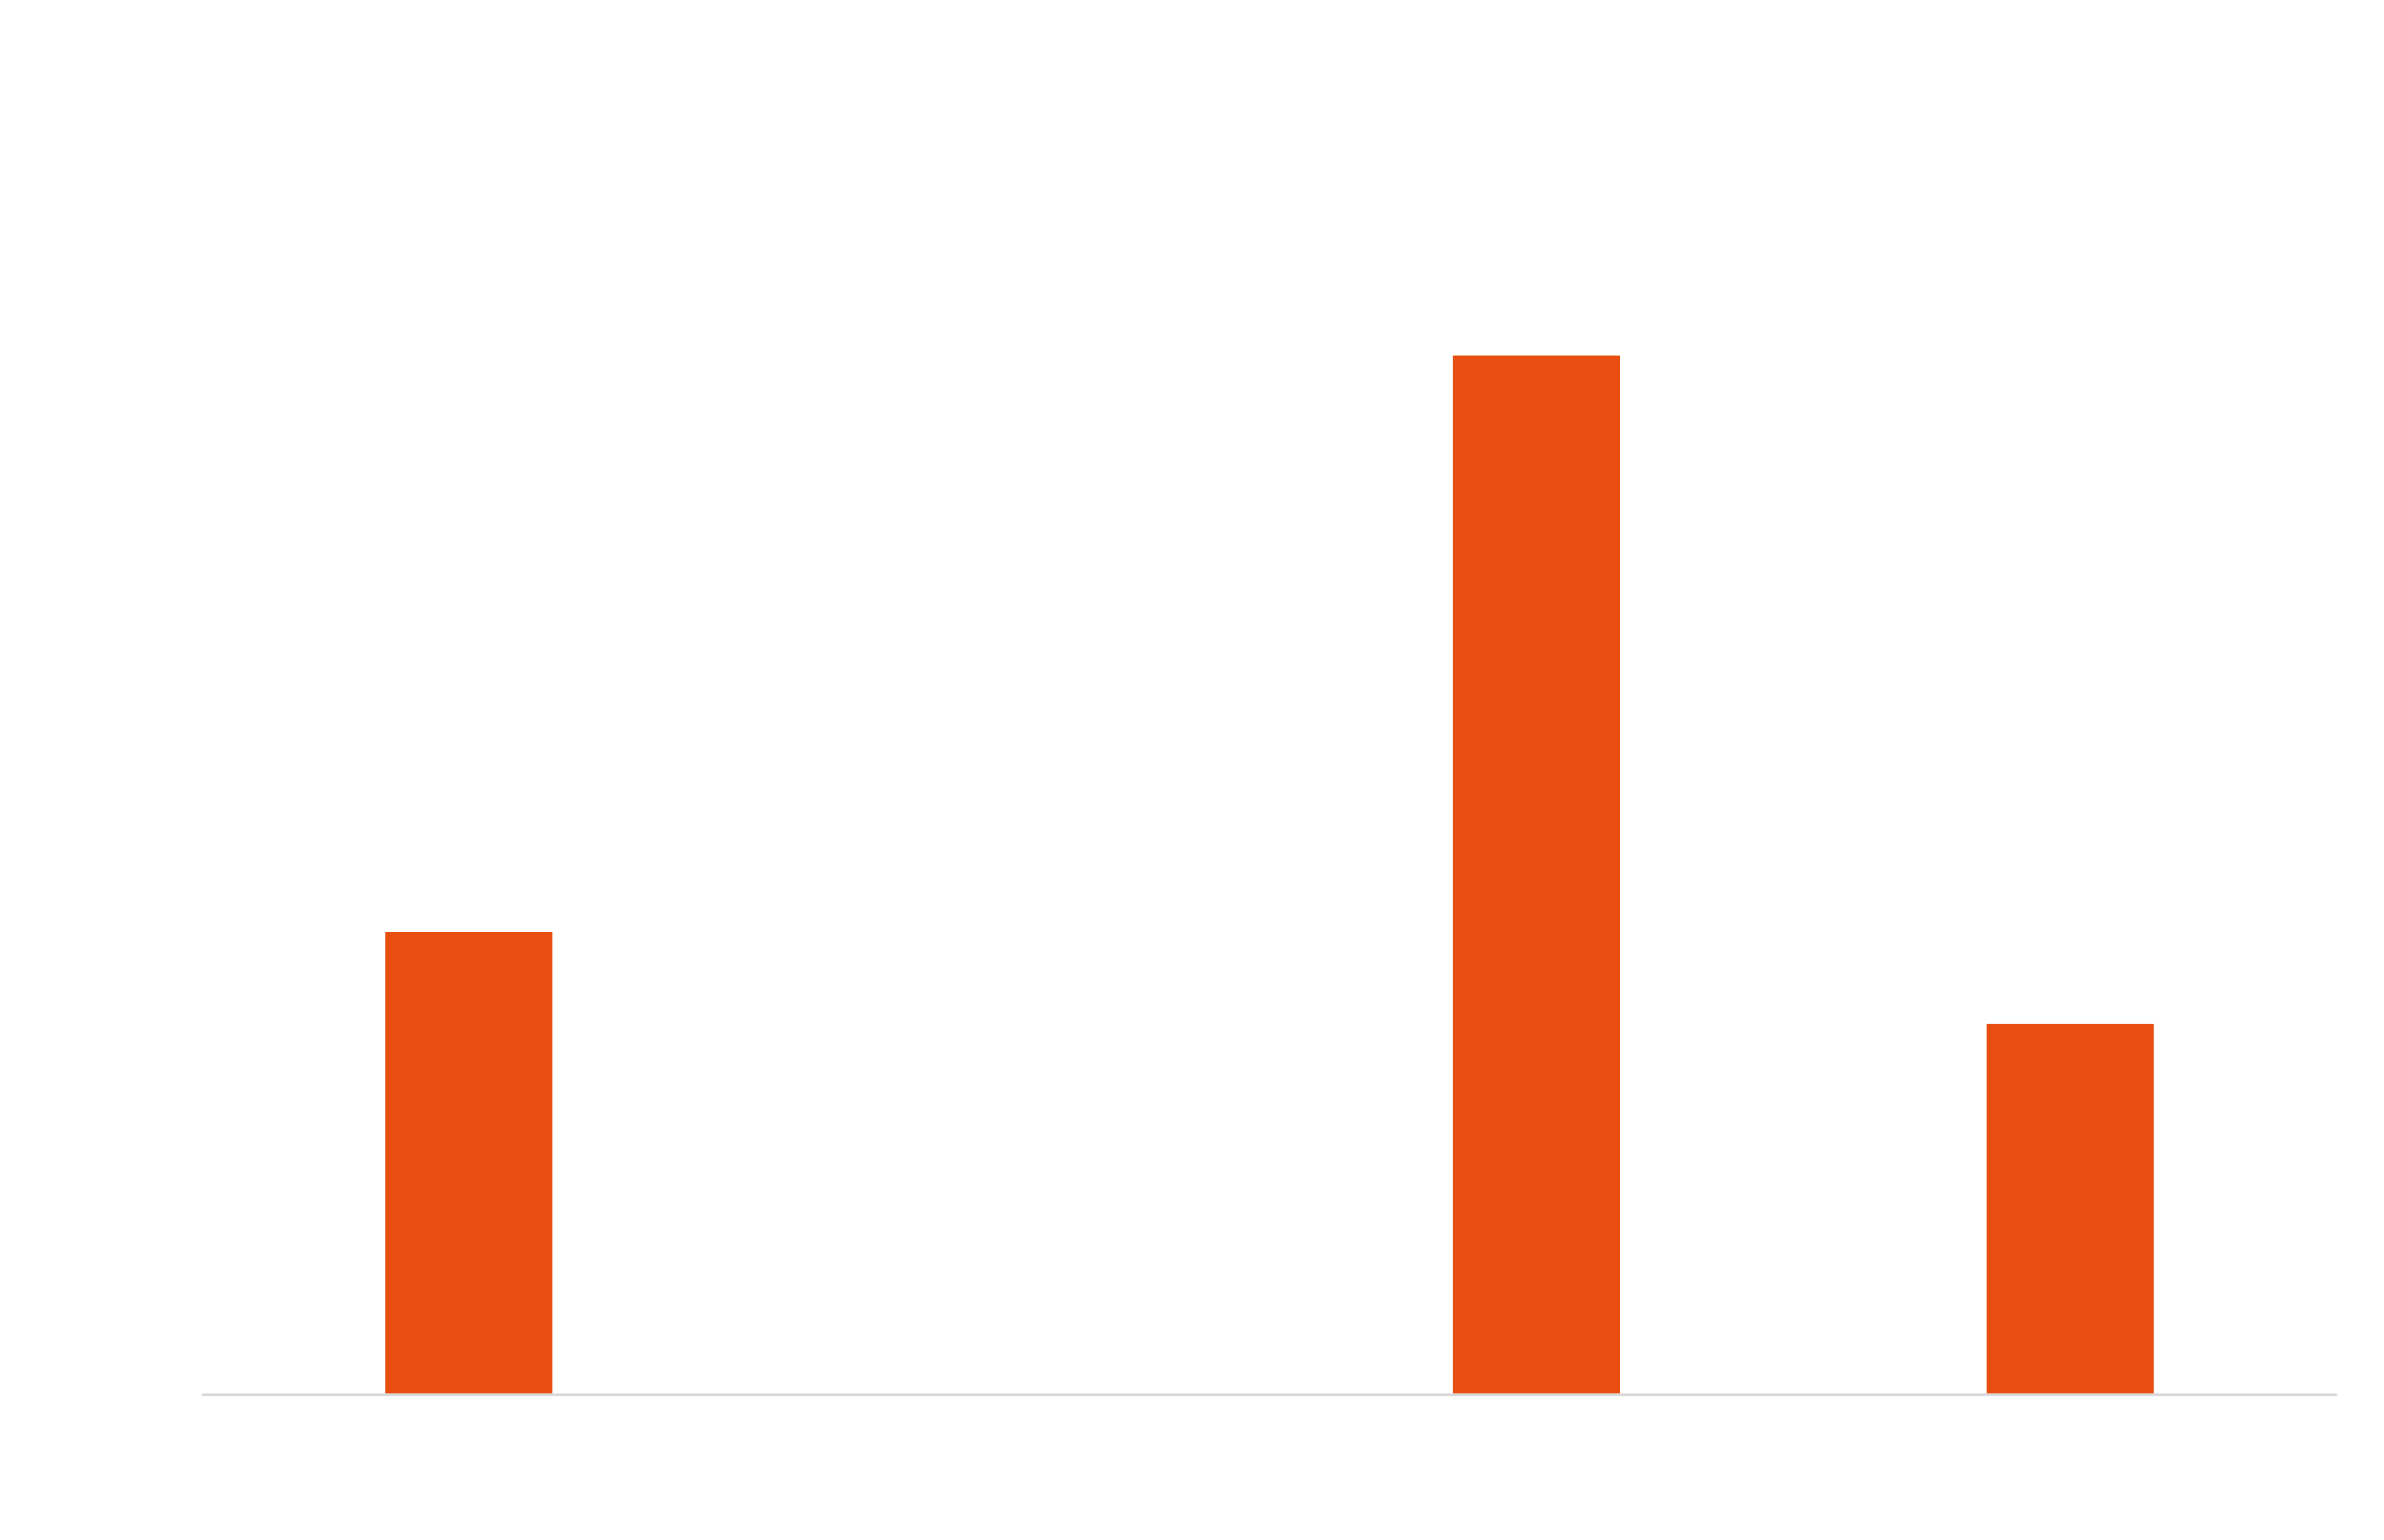
- Scheduled maintenance at Mazara, where TransMed reaches Sicily, cut flows to Italy by 58% in August 2024. PSV rose to nearly €3/MWh above TTF, a 16-month high.
- An inspection on Medgaz flipped PVB from a discount to TTF to a premium, a swing of about €1/MWh.
This suggests the link between Algerian supply and southern prices does work: when volumes are interrupted, spreads react. Political events had a less durable effect. The MEG closure pushed the Spanish forward spread up almost fourfold in the week it happened, but the move reversed, and Spain spent 2022 around €25/MWh below TTF. When Algiers threatened to cancel Spanish contracts, prices showed little reaction.
There are two ways to read this:
Reading A: there is a political risk premium. On this view, the premium exists but is hard to measure. The MEG closure did lift the spread sharply, flow cuts widen southern spreads by around €1/MWh, and unpredictable supply decisions widen bid-ask spreads around every outage, making gas more expensive to trade.
Reading B: the risk moved rather than being priced. The MEG closure halved Spain's pipeline capacity from Algeria, so Spain bought more LNG instead. When the Strait of Hormuz closed in March 2026 and cut off about a fifth of global LNG trade, Spanish hub prices rose 46%. Over the same period, Italy's premium over TTF narrowed, partly because Italy still relies on Algerian pipeline gas. On this view, the political risk may not have vanished so much as shifted into how buyers structure their supply portfolios, the terms of their contracts and the investment that never went into Algerian gas fields.
Both readings point in a similar direction. Political events have moved the spread, but so far only briefly and around the moment of decision. In the data available, they have not left a lasting premium.
Southern hubs carry more of the exposure
Europe's gas hubs are not equally exposed to Algeria:
- PSV (Italy) carries the highest exposure. Algeria supplied about 36% of Italy's gas last year.
- PVB (Spain) carries the second-highest exposure. Algeria is back as Spain's largest supplier, with about 35%, ahead of US LNG.
- THE (Germany) has low exposure, because it draws on Norway and a wide range of other suppliers through several routes.
- NBP (UK) also has low exposure. Norway provides about 65% of its supply, and interconnectors add flexibility.
- TTF (Netherlands) is the benchmark hub that the others are measured against.
Europe does not have a single gas market with a single risk profile. Exposure rises from north to south, and Algeria is one of the reasons behind that gradient. That exposure shows up in supply volumes and route optionality, not necessarily in prices in the long term.
Two rival pipelines for the Sahara
The same rivalry is shaping future supply. Two projects are competing to bring gas from West Africa to Europe:
- The Trans-Saharan Gas Pipeline (TSGP) would run 4,128 km from Nigeria through Niger into Algeria's network, carrying 30 bcm a year. No budget has been disclosed. Construction on the Algerian section began in June 2026 at Aoulef, in Adrar province, and work in Niger is due to start in early 2027. The project would strengthen Algeria's position as the gateway for this gas into Europe.
- The Nigeria-Morocco Gas Pipeline (NMGP) would follow the Atlantic coast for about 6,800 km. It would also carry 30 bcm a year, at an estimated cost of $25 billion, and it is designed to bypass Algeria entirely. ECOWAS heads of state signed an agreement backing it on July 19, 2026. A final investment decision is targeted for the end of 2026, with the first phase due to start operating in the second quarter of 2031.
The two projects are competing as much on politics as on cost. Whichever one advances is likely to shape who controls West African gas flowing to Europe, and could build the rivalry between Morocco and Algeria into Europe's energy security for decades.
What this means for European hub pricing
For anyone who trades, hedges or models European gas, there are four conclusions:
- Algerian risk has shown up in spreads, but only briefly. Political events do not seem to have left a lasting mark on hub prices, as markets renormalized.
- The risk is more to volume than to price. In 2025 Algeria's domestic use overtook its exports for the first time. After the Hormuz closure, European buyers turned to Algiers for more gas, yet flows to Spain still fell 6.9% in March and 13.1% in June (CORES, 2026). Demand for Algerian gas rose, but supply did not rise with it.
- Route optionality is a key exposure. Since the MEG closed, Spain has had only one pipeline from Algeria. It ran at 91% of capacity last year, which leaves little room to switch if something goes wrong.
- Fragmentation cuts both ways. From 2030, the EU's methane regulation will penalize emissions across the gas supply chain, and it could become one of the biggest barriers to Algerian gas. The EU's REPowerEU plan also assumes no increase in Algerian volumes. As a result, Algeria is being asked to commit to exploration licensing that runs for decades, with limited visibility on long-term European demand.
Algerian politics is difficult to model. Its effects on physical gas flows are easier to track.
The paradox is the signal
Algeria has the capacity to stabilize Europe's gas supply, a geopolitical position that can disrupt it and growing domestic demand that keeps more of its gas at home. Having pipelines is not the same as delivering gas through them. Algeria's own demand is increasingly a constraint alongside politics, and the risk falls mainly on Southern European hubs. That risk is best tracked through physical data: nominations, capacity bookings and contracted volumes.
Algeria has a strong record of honoring the contracts it signs. The open question for Europe is how much gas will be available behind them.